

Cherry: The Smarter Way to Pay
4.5

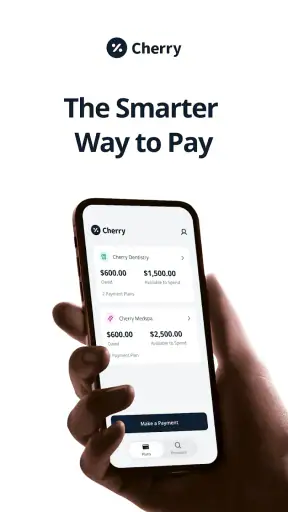
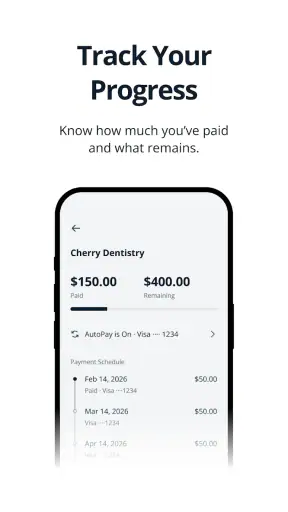
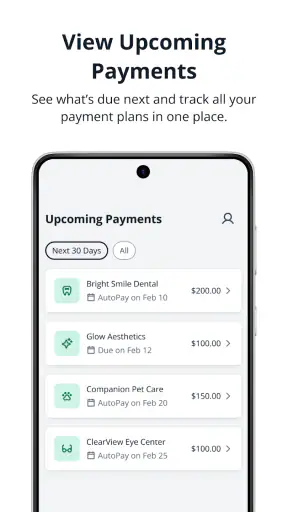
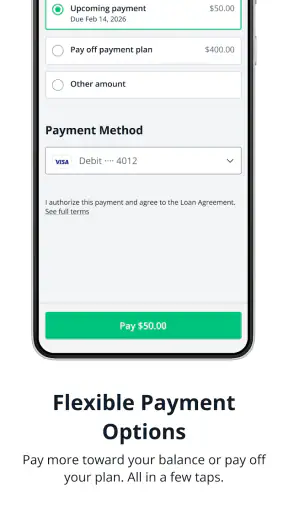
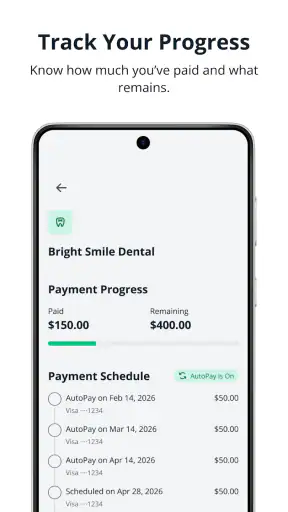
I approached Cherry: The Smarter Way to Pay as a finance app for people who want more control over payment timing rather than another tool focused mainly on tracking spending. Its central promise is simple: help users manage plans and pay on a schedule. In practice, that makes the app most interesting when a purchase or obligation needs more deliberate timing than a standard one-time payment allows.
My first impression is that Cherry is easier to understand when viewed as a planning companion, not a complete replacement for a bank account or a full budgeting suite. That distinction matters. If you want detailed category reports, investment monitoring, or a broad household ledger, this is probably not where I would start. If your immediate concern is organizing planned payments and keeping a clearer view of when money needs to leave your account, its focused approach makes more sense.
How Cherry feels in its current form
Cherry Technologies, Inc. is the developer behind the app, which is available as a free finance application for everyone. The current release is version 1.3.0, and the app has reached over one hundred thousand installs. Its average rating sits at 4.5 from around one hundred thirty ratings, with roughly fifty written reviews, so there is enough early user response to suggest that the basic idea is connecting with people, while the relatively modest review volume means I would still treat broad conclusions carefully.
The strongest part of the experience is the mental model. Instead of forcing every payment into a vague “spent” bucket, Cherry encourages me to think in terms of plans and schedules. That is useful for recurring obligations, planned purchases, or any payment where the date matters as much as the amount. I find this more practical than a simple transaction list because a list tells me what already happened; a plan helps me prepare for what is coming.
That focus also keeps the app from feeling unnecessarily crowded. Many finance products try to combine budgeting, credit information, coupons, investing, banking, and financial education in one place. Cherry takes a narrower route. For a user who feels overwhelmed by dashboards full of charts, this can be a welcome change. The trade-off is that users expecting a complete financial command center may find the experience intentionally limited.
The free price makes experimentation straightforward. I could evaluate whether its scheduling approach fits my routine without committing money first. That is particularly useful for someone who has tried traditional budgeting apps and found that they record activity well but do not help enough with the timing of upcoming payments.
A realistic monthly routine
Imagine I have several obligations arriving at different points in the month, alongside a planned purchase that I do not want to pay all at once. With a conventional notes app, I might write down the amounts and dates, then rely on memory to revisit them. A bank app may show completed transactions and current balances, but it may not present my intentions in a way that feels actionable. Cherry’s plan-centered approach gives me a place to organize those commitments and think through the payment schedule before the deadline arrives.
The practical benefit is not just seeing a date. It is separating a decision from the moment money actually leaves. I can consider whether a plan fits my upcoming commitments instead of making a rushed choice at checkout or when a reminder appears. That makes Cherry more useful as a preparation tool than as a passive financial diary.
There is also a subtle behavioral advantage here: scheduled thinking can expose conflicts earlier. If two planned payments overlap with a tight week, I can notice the problem while there is still time to adjust. A basic expense tracker may only show the damage afterward. For me, that is one of the app’s more valuable ideas, even though it is easy to overlook when reading a short store description.
What the current release tells me
The release history visible through the current version gives Cherry a sense of an actively developing product rather than a finished, feature-heavy financial platform. I would interpret version 1.3.0 as evidence that the team is refining the experience, not as proof that every advanced finance workflow is already covered. That distinction is important for anyone deciding whether to move an entire payment routine into the app.
For an existing user, a newer release can be encouraging because it suggests the product is still receiving attention. At the same time, I would avoid assuming that an update automatically changes the app’s role. The core value remains the organization of plans and payment timing. Users who already like that workflow should have a clearer reason to stay engaged; users waiting for a broad budgeting system should judge the app by what it does today rather than by what future releases might add.
I also think the version number changes how I would introduce Cherry to someone else. I would recommend starting with one type of plan, such as a recurring household obligation or a planned purchase, rather than transferring every financial detail immediately. That small trial reveals whether the scheduling model actually improves decision-making in the user’s daily life.
Where it helps existing users most
People already using Cherry are likely to benefit most when they treat it as a forward-looking layer. I would begin by entering plans that have a clear purpose and date, then review them before adding more. This avoids turning the app into another cluttered list and makes it easier to see which commitments deserve attention.
A useful workflow is to review plans at the same time as checking a bank balance. The two tools answer different questions: the bank shows what is available and what has happened, while Cherry is intended to help organize what I intend to pay and when. Keeping those roles separate reduces the risk of mistaking a planned payment for a completed one.
Another non-obvious use is as a pause mechanism for discretionary spending. A planned purchase does not have to be an urgent bill. Recording it as a future payment gives me a chance to reconsider the timing, compare it with other commitments, and decide whether it still belongs in the month ahead. This is more disciplined than relying on a shopping list, because the financial consequence stays visible.
I would also avoid creating duplicate plans for the same obligation merely because the payment date changes. A clean schedule is more valuable than a crowded history of abandoned intentions. If a plan needs adjustment, the best habit is to keep the current version understandable and remove or revise outdated entries according to the app’s available controls.
Where the experience still feels limited
Cherry’s narrow purpose is also its main limitation. I would not choose it as my only financial tool if I needed detailed spending analysis, investment views, tax preparation, or a complete shared household budget. A traditional budgeting app is usually better for comparing income with categories over time, while a banking app remains the natural place to verify balances and completed transactions.
There is another important boundary: planning is not the same as payment execution. The app’s identity centers on managing plans and paying on a schedule, but I would still verify the actual payment status through the relevant financial service or account. A plan can be organized correctly and still require separate confirmation. That extra check may feel like friction, but it is preferable to treating a schedule as proof that a transaction has settled.
Users who dislike entering information manually may also need patience. A focused planning experience depends on keeping plans current. If I create an entry and never revisit it after the amount or date changes, the app becomes less trustworthy as a decision aid. Cherry is therefore a better match for someone willing to maintain a small routine than for someone looking for a completely automatic financial overview.
The app may also be less suitable for people who want extensive customization before they understand the basics. I prefer starting with a few meaningful plans, but users managing complicated payment arrangements may want more detail than a streamlined interface is designed to provide. In that situation, a spreadsheet or a fuller budgeting platform could offer more control, even if it requires more work.
Cherry compared with familiar alternatives
Compared with a bank’s built-in tools, Cherry appears more focused on intentional payment planning. A bank app is excellent for checking available funds, confirming transactions, and handling account activity. It may not present future commitments in the same way. I would use the bank for verification and Cherry for organizing the plan, rather than expecting one to replace the other.
Compared with a notes app or calendar, Cherry has a more finance-specific purpose. A calendar can remind me that something is due, but it does not naturally frame the reminder as part of a payment plan. Notes are flexible, yet that flexibility can become messy. Cherry’s advantage is the attempt to give planned payments their own structure.
Compared with a full budgeting application, the decision is less about which product is universally better and more about what I need to see. A budgeting suite is the stronger choice if I want historical reports, category limits, and a broad view of household finances. Cherry is more appealing when the immediate problem is timing: what I intend to pay, when I intend to pay it, and how that plan fits into the next stretch of my finances.
That comparison also explains why I would not recommend replacing every existing tool on the first day. Cherry can complement a bank app or budget tracker without competing with every feature they offer. Used as a focused layer, it has a clearer job and is less likely to create duplicated records.
Questions I would answer before installing
Is Cherry suitable for a beginner? I think so, especially for someone who understands the basic difference between a planned payment and a completed transaction. The interface concept is easier to approach when I begin with one or two familiar obligations. A beginner who expects the app to automatically solve every budgeting decision may be disappointed, but a beginner looking for a simple planning habit has a reasonable starting point.
Can it replace a banking app? I would not treat it that way. The banking app remains important for account balances, transaction confirmation, and the actual financial record. Cherry’s value is in organizing plans and payment timing. Keeping both roles clear is the safest and most useful way to use it.
Who should skip it? I would suggest skipping Cherry if your main goal is investment management, detailed expense categorization, or a comprehensive financial dashboard. I would also hesitate if you know you will not update plans when circumstances change. An outdated schedule can create false confidence, which defeats the purpose of planning.
Is it worth trying when it is free? Yes, provided you test it with a contained workflow. I would choose a recurring obligation or a planned purchase, use it through one payment cycle, and then decide whether its view is genuinely helping me anticipate commitments. That test is more revealing than judging the app by its short description alone.
Does the current release make it a safe long-term choice? I see the current version as a reasonable point to evaluate the product, especially because the app is still developing. I would keep expectations grounded: use the features available now, retain normal payment verification habits, and watch future updates for improvements that directly affect the planning workflow rather than assuming every hoped-for feature is coming.
What I would watch as Cherry evolves
The most meaningful future progress would be anything that makes plans easier to maintain without weakening clarity. I would watch for smoother handling of changed dates, clearer distinctions between planned and completed payments, and tools that help users review upcoming commitments without turning the app into an overloaded dashboard. Those improvements would strengthen the product’s central idea rather than pull it in unrelated directions.
I would also pay attention to how the app serves people with more than a handful of plans. A simple workflow is excellent at the beginning, but organization becomes harder when obligations, purchases, and adjustments accumulate. The best evolution would preserve the approachable feel while giving experienced users enough control to keep a busy schedule readable.
Another area worth watching is the relationship between Cherry and the financial tools people already use. The app does not need to imitate a bank to be useful, but it should make its role beside a bank or budgeting tool obvious. Clear boundaries, reliable status cues, and a low-effort review routine would make it easier to trust without encouraging users to abandon essential verification elsewhere.
My overall view is positive but deliberately practical. Cherry offers a focused way to think about payment plans and timing, and that can solve a real everyday problem that ordinary transaction histories often leave untouched. Its free access, Everyone age rating, and growing presence make it easy to test, while the 4.5 average suggests a generally favorable early reception.
I would recommend it to someone who wants a calmer, more forward-looking payment routine and is comfortable keeping plans updated. I would not recommend it as a replacement for a bank account, a detailed budgeting system, or an investment app. Its real strength is helping a user prepare for payments before they become urgent, and its real weakness is that this benefit depends on honest, regular maintenance.
After using it, I would keep Cherry in a supporting role: check the schedule before making a discretionary purchase, compare planned commitments with the bank balance, and confirm completed payments through the appropriate financial account. That approach gives the app room to do what it does best without asking it to become something it is not. For the right user, that focused role is precisely what makes it worth trying.
4.5
50.00 Reviews
Pros
- Splits purchases into manageable installments for better cash-flow control.
- Clear repayment schedules help users understand upcoming payment dates.
- Fast application process with a simple
- mobile-first interface.
- Can make larger purchases more accessible without using a credit card.
- Useful payment reminders can help reduce the chance of missed installments.
Cons
- Approval and spending limits may vary based on your financial profile.
- Late or missed payments can lead to fees or account restrictions.
- Installment plans may cost more than paying the full price upfront.
- Not every retailer or purchase category may be supported.
- Requires sharing personal and financial information during verification.


